
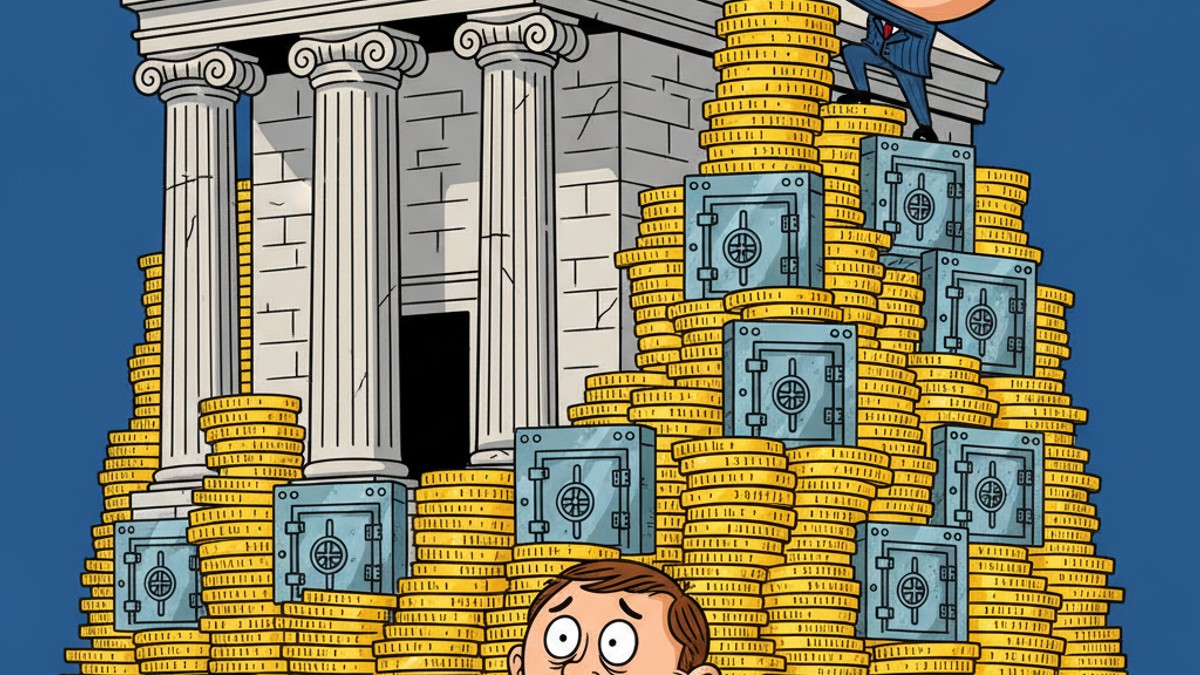
Imagine a bank having to keep a “rainy day fund” — its own money that it cannot lend out, held aside for bad times. Well, that fund is about to get bigger. On September 30, 2026, the Croatian National Bank (HNB) set a new countercyclical capital buffer rate: as of October 1, 2027, banks will have to hold 2.25% of their risk-weighted exposures as additional protective capital. The decision was published in the Official Gazette (NN 112/2026, October 2, 2026) and signed by Governor Ante Žigman.
Sounds like a banking internal matter? Partly, yes. But this figure — and its direction — says a lot about where loans, interest rates, and your borrowing capacity are headed. Let’s go step by step.
What is the countercyclical capital buffer, really?
A bank is not a shop. If too many loans turn bad, the same bank that gave you a mortgage can become a problem for everyone — from depositors to the state budget. That is why the law requires banks to hold capital buffers on top of minimum capital: extra capital that cannot be “spent” on day-to-day business.
The countercyclical buffer is special because it works against the cycle: it goes up when credit grows too fast (to cool down an overheating economy) and comes down when a crisis hits (so banks have “fuel” to keep lending instead of slamming the brakes all at once). In short — a shock absorber for the economy, and a signal to banks not to chase growth at any cost.
The new rate was set under the Credit Institutions Act (Official Gazette no. 22/2026) and the EU prudential requirements regulation (Regulation (EU) No 575/2013, the CRR).
How the rate has grown: a short history of the cushion
| Rate | Effective from | Decision |
|---|---|---|
| 1.0% | Dec 31, 2023 | NN 148/2022 |
| 1.5% | Jun 30, 2024 | NN 72/2023 |
| 2.0% | Jan 1, 2027 | NN 149/2025 |
| 2.25% | Oct 1, 2027 | NN 112/2026 |
Notice the rhythm: back in December 2025, HNB announced 2.0% from the start of 2027 — and by October 2026 it already raised the target to 2.25% from October 2027. The message is clear: the banking sector is getting a bigger cushion, not a smaller one, in an unbroken series of hikes since 2022.
Why is HNB tightening?
- Fast credit growth. Especially in housing — property prices in Croatia keep rising faster than wages, and credit growth follows that trend.
- A signal to the market. When a central bank raises the buffer, banks automatically become more cautious about new lending — that is the whole point.
- Part of a bigger story. In late September, HNB already tightened conditions for housing loans, and banks raised their rates — we wrote about it here. Now it is the banks’ own capital that gets the squeeze.
- European context. The ESRB (European Systemic Risk Board) has for years recommended stronger macroprudential buffers in countries with fast-rising property prices. Croatia is following that advice to the letter.
What it means for your loans (and what it does NOT mean)
First, the most important part: it does not directly touch your monthly payment. This is not a tax on loans, not a fee, and it will not hike your rate overnight. Your deposits remain insured up to €100,000 under the deposit insurance scheme.
But indirectly — yes, there are effects:
- Capital has a cost. Banks must raise more “safe” equity capital for the same volume of loans. That costs them money, so the long-term pressure on lending prices is gently upward — one reason rates are already climbing.
- Approval can get stricter. More capital means more caution. Banks will look even more carefully at your creditworthiness, your debt-to-income ratio, and the property’s value.
- Time is on your side. The rate applies only from October 1, 2027. If you are planning a loan, the period until then is probably the last “soft” window before further tightening.
What to do with this information
- Don’t panic. For most people the effect is invisible — this is a brake on banks, not a penalty on borrowers.
- If you plan a mortgage — compare offers and consider a fixed rate while rate wars are still alive. HNB measures and buffers all point the same way: loans will get pricier and stricter, not cheaper.
- Watch your debt level. If the central bank is raising buffers, it sees risk in credit growth. Your personal version of that: don’t borrow up to your absolute maximum.
- Mind the rate type. A variable rate is risk; a fixed rate is predictability. Choose deliberately, not out of habit.
TL;DR
- HNB raised the countercyclical capital buffer to 2.25% (NN 112/2026, published Oct 2, 2026)
- Applies from October 1, 2027 — replacing the earlier decision (2.0% from Jan 1, 2027)
- Banks must hold more capital per unit of credit risk → more cautious lending and mild upward pressure on loan prices
- For your monthly payment: no direct effect — but the period until autumn 2027 is a good window for signing a loan on more favorable terms
- Deposits remain insured up to €100,000; this is neither a tax nor a fee
Sources: Official Gazette — NN 112/2026 (Oct 2, 2026), NN 149/2025, NN 72/2023, NN 148/2022; HNB.